Showing posts with label Federal Reserve. Show all posts

Monday, November 17, 2014

The Return of the Dollar

By John Mauldin


Two years ago, my friend Mohamed El-Erian and I were on the stage at my Strategic Investment Conference. Naturally we were discussing currencies in the global economy, and I asked him about currency wars. He smiled and said to me, “John, we don’t talk about currency wars in polite circles. More like currency disagreements” (or some word to that effect).

This week I note that he actually uses the words currency war in an essay he wrote for Project Syndicate:

Yet the benefits of the dollar’s rally are far from guaranteed, for both economic and financial reasons. While the US economy is more resilient and agile than its developed counterparts, it is not yet robust enough to be able to adjust smoothly to a significant shift in external demand to other countries. There is also the risk that, given the role of the ECB and the Bank of Japan in shaping their currencies’ performance, such a shift could be characterized as a “currency war” in the US Congress, prompting a retaliatory policy response.

This is a short treatise, but as usual with Mohamed’s writing, it’s very thought provoking. Definitely Outside the Box material.

And for a two-part Outside the Box I want to take the unusual step of including an op-ed piece that you might not have seen, from the Wall Street Journal, called “How to Distort Income Inequality,” by Phil Gramm and Michael Solon. They cite research I’ve seen elsewhere which shows that the work by Thomas Piketty cherry-picks data and ignores total income and especially how taxes distort the data. That is not to say that income inequality does not exist and that we should not be cognizant and concerned, but we need to plan policy based on a firm grasp of reality and not overreact because of some fantasy world created by social provocateur academicians.

This weeks new video "How you can Profit from ETFs on the Unexpected Move in the Dollar".....Just Click Here

The calls for income redistribution from socialists and liberals based on Piketty’s work are clearly misguided and will further distort income inequality in ways that will only reduce total global productivity and growth.
I’m in New York today at an institutional fund manager conference where I had the privilege of hearing my good friend Ian Bremmer take us around the world on a geopolitical tour. Ian was refreshingly optimistic, or at least sanguine, about most of the world over the next few years. Lots of potential problems, of course, but he thinks everything should turn out fine – with the notable exception of Russia, where he is quite pessimistic.

A shirtless Vladimir Putin was the scariest thing on his geopolitical radar. As he spoke, Russia was clearly putting troops and arms into eastern Ukraine. Why would you do that if you didn’t intend to go further? Ian worried openly about Russia’s extending a land bridge all the way to Crimea and potentially even to Odessa, which is the heart of economic Ukraine, along with the Kiev region. It would basically make Ukraine ungovernable.

I thought Putin’s sadly grim and memorable line that “The United States is prepared to fight Russia to the last Ukrainian” pretty much sums up the potential for a US or NATO response. Putin agreed to a cease-fire and assumed that sanctions would start to be lifted. When there was no movement on sanctions, he pretty much went back to square one. He has clearly turned his economic attention towards China.

Both Ian Bremmer and Mohamed El Erian will be at my Strategic Investment Conference next year, which will again be in San Diego in the spring, April 28-30. Save the dates in your calendar as you do not want to miss what is setting up to be a very special conference. We will get more details to you soon.

It is a very pleasant day here in New York, and I was able to avoid taxis and put in about six miles of pleasant walking. (Sadly, it is supposed to turn cold tomorrow.) I’ve gotten used to getting around in cities and slipping into the flow of things, but there was a time when I felt like the country mouse coming to the city. As I walked past St. Bart’s today I was reminded of an occasion when your humble analyst nearly got himself in serious trouble.

There is a very pleasant little outdoor restaurant at St. Bartholomew’s Episcopal Church, across the street from the side entrance of the Waldorf-Astoria. It was a fabulous day in the spring, and I was having lunch with my good friend Barry Ritholtz. The president (George W.) was in town and staying at the Waldorf. His entourage pulled up and Barry pointed and said, “Look, there’s the president.”

We were at the edge of the restaurant, so I stood up to see if I could see George. The next thing I know, Barry’s hand is on my shoulder roughly pulling me back into my seat. “Sit down!” he barked. I was rather confused – what faux pas I had committed? Barry pointed to two rather menacing, dark-suited figures who were glaring at me from inside the restaurant.

“They were getting ready to shoot you, John! They had their hands inside their coats ready to pull guns. They thought you were going to do something to the president!”

This was New York not too long after 9/11. The memory is fresh even today. Now, I think I would know better than to stand up with the president coming out the side door across the street. But back then I was still just a country boy come to the big city.

Tomorrow night I will have dinner with Barry and Art Cashin and a few other friends at some restaurant which is supposedly famous for a mob shooting back in the day. Art will have stories, I am sure.
It is time to go sing for my supper, and I will try not to keep the guests from enjoying what promises to be a fabulous meal from celebrity chef Cyrille Allannic. After Ian’s speech, I think I will be nothing but sweetness and light, just a harmless economic entertainer. After all, what could possibly go really wrong with the global economy, when you’re being wined and dined at the top of New York? Have a great week.

John Mauldin, Editor
Outside the Box
subscribers@mauldineconomics.com

Stay Ahead of the Latest Tech News and Investing Trends...

Each day, you get the three tech news stories with the biggest potential impact.

The Return of the Dollar

By Mohamed El-Erian
Project Syndicate, Nov. 13, 2014

The U.S. dollar is on the move. In the last four months alone, it has soared by more than 7% compared with a basket of more than a dozen global currencies, and by even more against the euro and the Japanese yen. This dollar rally, the result of genuine economic progress and divergent policy developments, could contribute to the “rebalancing” that has long eluded the world economy. But that outcome is far from guaranteed, especially given the related risks of financial instability.

Two major factors are currently working in the dollar’s favor, particularly compared to the euro and the yen. First, the United States is consistently outperforming Europe and Japan in terms of economic growth and dynamism – and will likely continue to do so – owing not only to its economic flexibility and entrepreneurial energy, but also to its more decisive policy action since the start of the global financial crisis.

Second, after a period of alignment, the monetary policies of these three large and systemically important economies are diverging, taking the world economy from a multi-speed trajectory to a multi-track one. Indeed, whereas the US Federal Reserve terminated its large-scale securities purchases, known as “quantitative easing” (QE), last month, the Bank of Japan and the European Central Bank recently announced the expansion of their monetary-stimulus programs. In fact, ECB President Mario Draghi signaled a willingness to expand his institution’s balance sheet by a massive €1 trillion ($1.25 trillion).

With higher US market interest rates attracting additional capital inflows and pushing the dollar even higher, the currency’s revaluation would appear to be just what the doctor ordered when it comes to catalyzing a long-awaited global rebalancing – one that promotes stronger growth and mitigates deflation risk in Europe and Japan. Specifically, an appreciating dollar improves the price competitiveness of European and Japanese companies in the US and other markets, while moderating some of the structural deflationary pressure in the lagging economies by causing import prices to rise.

Yet the benefits of the dollar’s rally are far from guaranteed, for both economic and financial reasons. While the US economy is more resilient and agile than its developed counterparts, it is not yet robust enough to be able to adjust smoothly to a significant shift in external demand to other countries. There is also the risk that, given the role of the ECB and the Bank of Japan in shaping their currencies’ performance, such a shift could be characterized as a “currency war” in the US Congress, prompting a retaliatory policy response.

Furthermore, sudden large currency moves tend to translate into financial-market instability. To be sure, this risk was more acute when a larger number of emerging-economy currencies were pegged to the U.S. dollar, which meant that a significant shift in the dollar’s value would weaken other countries’ balance of payments position and erode their international reserves, thereby undermining their creditworthiness. Today, many of these countries have adopted more flexible exchange-rate regimes, and quite a few retain adequate reserve holdings.

But a new issue risks bringing about a similarly problematic outcome: By repeatedly repressing financial-market volatility over the last few years, central-bank policies have inadvertently encouraged excessive risk-taking, which has pushed many financial-asset prices higher than economic fundamentals warrant. To the extent that continued currency-market volatility spills over into other markets – and it will – the imperative for stronger economic fundamentals to validate asset prices will intensify.

This is not to say that the currency re-alignment that is currently underway is necessarily a problematic development; on the contrary, it has the potential to boost the global economy by supporting the recovery of some of its most challenged components. But the only way to take advantage of the re-alignment’s benefits, without experiencing serious economic disruptions and financial-market volatility, is to introduce complementary growth-enhancing policy adjustments, such as accelerating structural reforms, balancing aggregate demand, and reducing or eliminating debt overhangs.

After all, global growth, at its current level, is inadequate for mere redistribution among countries to work. Overall global GDP needs to increase.

The US dollar’s resurgence, while promising, is only a first step. It is up to governments to ensure that the ongoing currency re-alignment supports a balanced, stable, and sustainable economic recovery. Otherwise, they may find themselves again in the unpleasant business of mitigating financial instability.

How to Distort Income Inequality

By Phil Gramm and Michael Solon
Wall Street Journal, Nov. 11, 2014

The Piketty-Saez data ignore changes in tax law and fail to count noncash compensation and Social Security benefits.

What the hockey-stick portrayal of global temperatures did in bringing a sense of crisis to the issue of global warming is now being replicated in the controversy over income inequality, thanks to a now-famous study by Thomas Piketty and Emmanuel Saez, professors of economics at the Paris School of Economics and the University of California, Berkeley, respectively. Whether the issue is climate change or income inequality, however, problems with the underlying data significantly distort the debate.

The chosen starting point for the most-quoted part of the Piketty-Saez study is 1979. In that year the inflation rate was 13.3%, interest rates were 15.5% and the poverty rate was rising, but economic misery was distributed more equally than in any year since. That misery led to the election of Ronald Reagan, whose economic policies helped usher in 25 years of lower interest rates, lower inflation and high economic growth. But Messrs. Piketty and Saez tell us it was also a period where the rich got richer, the poor got poorer and only a relatively small number of Americans benefited from the economic booms of the Reagan and Clinton years.

If that dark picture doesn’t sound like the country you lived in, that’s because it isn’t. The Piketty-Saez study looked only at pretax cash market income. It did not take into account taxes. It left out noncash compensation such as employer-provided health insurance and pension contributions. It left out Social Security payments, Medicare and Medicaid benefits, and more than 100 other means-tested government programs. Realized capital gains were included, but not the first $500,000 from the sale of one’s home, which is tax-exempt. IRAs and 401(k)s were counted only when the money is taken out in retirement. Finally, the Piketty-Saez data are based on individual tax returns, which ignore, for any given household, the presence of multiple earners.

And now, thanks to a new study in the Southern Economic Journal, we know what the picture looks like when the missing data are filled in. Economists Philip Armour and Richard V. Burkhauser of Cornell University and Jeff Larrimore of Congress’s Joint Committee on Taxation expanded the Piketty-Saez income measure using census data to account for all public and private in-kind benefits, taxes, Social Security payments and household size.

The result is dramatic. The bottom quintile of Americans experienced a 31% increase in income from 1979 to 2007 instead of a 33% decline that is found using a Piketty-Saez market-income measure alone. The income of the second quintile, often referred to as the working class, rose by 32%, not 0.7%. The income of the middle quintile, America’s middle class, increased by 37%, not 2.2%.

By omitting Social Security, Medicare and Medicaid, the Piketty-Saez study renders most older Americans poor when in reality most have above-average incomes. The exclusion of benefits like employer-provided health insurance, retirement benefits (except when actually paid out in retirement) and capital gains on homes misses much of the income and wealth of middle- and upper-middle income families.

Messrs. Piketty and Saez also did not take into consideration the effect that tax policies have on how people report their incomes. This leads to major distortions. The bipartisan tax reform of 1986 lowered the highest personal tax rate to 28% from 50%, but the top corporate-tax rate was reduced only to 34%. There was, therefore, an incentive to restructure businesses from C-Corps to subchapter S corporations, limited liability corporations, partnerships and proprietorships, where the same income would now be taxed only once at a lower, personal rate. As businesses restructured, what had been corporate income poured into personal income-tax receipts.

So Messrs. Piketty and Saez report a 44% increase in the income earned by the top 1% in 1987 and 1988—though this change reflected how income was taxed, not how income had grown. This change in the structure of American businesses alone accounts for roughly one-third of what they portray as the growth in the income share earned by the top 1% of earners over the entire 1979-2012 period.

An equally extraordinary distortion in the data used to measure inequality (the Gini Coefficient) has been discovered by Cornell’s Mr. Burkhauser. In 1992 the Census Bureau changed the Current Population Survey to collect more in-depth data on high-income individuals. This change in survey technique alone, causing a one-time upward shift in the measured income of high-income individuals, is the source of almost 30% of the total growth of inequality in the U.S. since 1979.

Simple statistical errors in the data account for roughly one third of what is now claimed to be a “frightening” increase in income inequality. But the weakness of the case for redistribution does not end there. America is the freest and most dynamic society in history, and freedom and equality of outcome have never coexisted anywhere at any time. Here the innovator, the first mover, the talented and the persistent win out—producing large income inequality. The prizes are unequal because in our system consumers reward people for the value they add. Some can and do add extraordinary value, others can’t or don’t.

How exactly are we poorer because Bill Gates, Warren Buffett and the Walton family are so rich? Mr. Gates became rich by mainstreaming computer power into our lives and in the process made us better off. Mr. Buffett’s genius improves the efficiency of capital allocation and the whole economy benefits. Wal-Mart stretches our buying power and raises the living standards of millions of Americans, especially low-income earners. Rich people don’t “take” a large share of national income, they “bring” it. The beauty of our system is that everybody benefits from the value they bring.

Yes, income is 24% less equally distributed here than in the average of the other 34 member countries of the OECD. But OECD figures show that U.S. per capita GDP is 42% higher, household wealth is 210% higher and median disposable income is 42% higher. How many Americans would give up 42% of their income to see the rich get less?

Vast new fortunes were earned in the 25-year boom that began under Reagan and continued under Clinton. But the income of middle-class Americans rose significantly. These incomes have fallen during the Obama presidency, and not because the rich have gotten richer. They’ve fallen because bad federal policies have yielded the weakest recovery in the postwar history of America.

Yet even as the recovery continues to disappoint, the president increasingly turns to the politics of envy by demanding that the rich pay their “fair share.” The politics of envy may work here as it has worked so often in Latin America and Europe, but the economics of envy is failing in America as it has failed everywhere else.

Mr. Gramm, a former Republican senator from Texas, is a visiting scholar at the American Enterprise Institute. Mr. Solon was a budget adviser to Senate Republican Leader Mitch McConnell and is a partner of US Policy Metrics.

Like Outside the Box?

Sign up today and get each new issue delivered free to your inbox.
It's your opportunity to get the news John Mauldin thinks matters most to your finances.


Important Disclosures

The article Outside the Box: The Return of the Dollar was originally published at mauldineconomics.com.


Get our latest FREE eBook "Understanding Options"....Just Click Here!

Tuesday, November 19, 2013

The Unintended Consequences of ZIRP

By John Mauldin


Yellen's coronation was this week. Art Cashin mused that it was a wonder some senator did not bring her a corsage: it was that type of confirmation hearing. There were a few interesting questions and answers, but by and large we heard what we already knew. And what we know is that monetary policy is going to be aggressively biased to the easy side for years, or at least that is the current plan. Far more revealing than the testimony we heard on Thursday were the two very important papers that were released last week by the two most senior and respected Federal Reserve staff economists. As Jan Hatzius at Goldman Sachs reasoned, it is not credible to believe that these papers and the thinking that went into them were not broadly approved by both Ben Bernanke and Janet Yellen.

Essentially the papers make an intellectual and theoretical case for an extended period of very low interest rates and, in combination with other papers from both inside and outside the Fed from heavyweight economists, make a strong case for beginning to taper sooner rather than later, but for accompanying that tapering with a commitment to an even more protracted period of ZIRP (zero interest rate policy). In this week's letter we are going analyze these papers, as they are critical to understanding the future direction of Federal Reserve policy. Secondly, we'll look at what I think may be some of the unintended consequences of long-term ZIRP.

We are going to start with an analysis by Gavyn Davies of the Financial Times. He writes on macroeconomics and is one of the more of the astute observers I read. I commend his work to you. Today, rather than summarize his analysis, I feel it is more appropriate to simply quote parts of it. (I will intersperse comments, unindented.) The entire piece can be found here.

While the markets have become obsessively focused on the date at which the Fed will start to taper its asset purchases, the Fed itself, in the shape of its senior economics staff, has been thinking deeply about what the stance of monetary policy should be after tapering has ended. This is reflected in two papers to be presented to the annual IMF research conference this week by William English and David Wilcox, who have been described as two of the most important macro-economists working for the FOMC at present. At the very least, these papers warn us what the FOMC will be hearing from their staff economists in forthcoming meetings.

The English paper extends the conclusions of Janet Yellen's "optimal control speeches" in 2012, which argued for pre-committing to keep short rates "lower-for-longer" than standard monetary rules would imply. The Wilcox paper dives into the murky waters of "endogenous supply", whereby the Fed needs to act aggressively to prevent temporary damage to US supply potential from becoming permanent. The overall message implicitly seems to accept that tapering will happen broadly on schedule, but this is offset by super-dovishness on the forward path for short rates.

The papers are long and complex, and deserve to be read in full by anyone seriously interested in the Fed's thought processes. They are, of course, full of caveats and they acknowledge that huge uncertainties are involved. But they seem to point to three main conclusions that are very important for investors.

1. They have moved on from the tapering decision.

Both papers give a few nods in the direction of the tapering debate, but they are written with the unspoken assumption that the expansion of the balance sheet is no longer the main issue. I think we can conclude from this that they believe with a fairly high degree of certainty that the start and end dates for tapering will not be altered by more than a few months either way, and that the end point for the total size of the balance sheet is therefore also known fairly accurately. From now on, the key decision from their point of view is how long to delay the initial hike in short rates, and exactly how the central bank should pre-commit on this question. By omission, the details of tapering are revealed to be secondary.

Yellen said as much in her testimony. In response to a question about QE, she said, "I would agree that this program [QE] cannot continue forever, that there are costs and risks associated with the program."
The Fed have painted themselves into a corner of their own creation. They are clearly very concerned about the stock market reaction even to the mere announcement of the onset of tapering. But they also know they cannot continue buying $85 billion of assets every month. Their balance sheet is already at $4 trillion and at the current pace will expand by $1 trillion a year. Although I can find no research that establishes a theoretical limit, I do believe the Fed does not want to find that limit by running into a wall. Further, it now appears that they recognize that QE is of limited effectiveness with market valuations where they are, and so for practical purposes they need to begin to withdraw QE.

But rather than let the market deal with the prospect of an end to an easy monetary policy (which everyone recognizes has to draw to an end at some point), they are now looking at ways to maintain the illusion of the power of the Federal Reserve. And they are right to be concerned about the market reaction, as was pointed out in a recent note from Ray Dalio and Bridgewater, as analyzed by Zero Hedge:

"The Fed's real dilemma is that its policy is creating a financial market bubble  that is large relative to the pickup in the economy that it is producing," Bridgewater notes, as the relationship between US equity markets and the Fed's balance sheet (here and here for example) and "disconcerting disconnects" (here and here) indicate how the Fed is "trapped." However, as the incoming Yellen faces up to her "tough" decisions to taper or not, Ray Dalio's team is concerned about something else – "We're not worried about whether the Fed is going to hit or release the gas pedal, we're worried about whether there's much gas left in the tank and what will happen if there isn't."

Dalio then outlines their dilemma neatly. "…The dilemma the Fed faces now is that the tools currently at its disposal are pretty much used up, in that interest rates are at zero and US asset prices have been driven up to levels that imply very low levels of returns relative to the risk, so there is very little ability to stimulate from here if needed. So the Fed will either need to accept that outcome, or come up with new ideas to stimulate conditions."

The new ideas that Bridgewater and everyone else are looking for are in the papers we are examining. Returning to Davies work (emphasis below is mine!):

2. They think that "optimal" monetary policy is very dovish indeed on the path for rates.

Both papers conduct optimal control exercises of the Yellen-type. These involve using macro-economic models to derive the path for forward short rates that optimise the behaviour of inflation and unemployment in coming years. The message is familiar: the Fed should pre-commit today to keep short rates at zero for a much longer period than would be implied by normal Taylor Rules, even though inflation would temporarily exceed 2 per cent, and unemployment would drop below the structural rate. This induces the economy to recover more quickly now, since real expected short rates are reduced.

Compared to previously published simulations, the new ones in the English paper are even more dovish. They imply that the first hike in short rates should be in 2017, a year later than before. More interestingly, they experiment with various thresholds that could be used to persuade the markets that the Fed really, really will keep short rates at zero, even if the economy recovers and inflation exceeds target. They conclude that the best way of doing this may be to set an unemployment threshold at 5.5 per cent, which is 1 per cent lower than the threshold currently in place, since this would produce the best mix of inflation and unemployment in the next few years. Such a low unemployment threshold has not been contemplated in the market up to now.

3. They think aggressively easy monetary policy is needed to prevent permanent supply side deterioration.

This theme has been mentioned briefly in previous Bernanke speeches, but the Wilcox paper elevates it to center stage. The paper concludes that the level of potential output has been reduced by about 7 per cent in recent years, largely because the rate of productivity growth has fallen sharply. In normal circumstances, this would carry a hawkish message for monetary policy, because it significantly reduces the amount of spare capacity available in the economy in the near term.

However, the key is that Wilcox thinks that much of the loss in productive potential has been caused by (or is "endogenous to") the weakness in demand. For example, the paper says that the low levels of capital investment would be reversed if demand were to recover more rapidly, as would part of the decline in the labour participation rate. In a reversal of Say's Law, and also a reversal of most US macro-economic thinking since Friedman, demand creates its own supply.

This concept is key to understanding current economic thinking. The belief is that it is demand that is the issue and that lower rates will stimulate increased demand (consumption), presumably by making loans cheaper for businesses and consumers. More leverage is needed! But current policy apparently fails to grasp that the problem is not the lack of consumption: it is the lack of income. Income is produced by productivity. When leverage increases productivity, that is good; but when it is used simply to purchase goods for current consumption, it merely brings future consumption forward. Debt incurred and spent today is future consumption denied. Back to Davies:

This new belief in endogenous supply clearly reinforces the "lower for longer" case on short rates, since aggressively easy monetary policy would be more likely to lead to permanent gains in real output, with only temporary costs in higher inflation. Whether or not any of this analysis turns out to be justified in the long run, it is surely important that it is now being argued so strongly in an important piece of Fed research. 

            Read that last sentence again. It makes no difference whether you and I might disagree with their analysis. They are at the helm, and unless something truly unexpected happens, we are going to get Fed assurances of low interest rates for a very long time. Davies concludes:

The implication of these papers is that these Fed economists have largely accepted in their own minds that tapering will take place sometime fairly soon, but that they simultaneously believe that rates should be held at zero until (say) 2017. They will clearly have a problem in convincing markets of this. After the events of the summer, bond traders have drawn the conclusion that tapering is a robust signal that higher interest rates are on the way. The FOMC will need to work very hard indeed to convince the markets, through its new thresholds and public pronouncements, that tapering and forward short rates really do need to be divorced this time. It could be a long struggle.

On a side note, we are beginning to see calls from certain circles to think about also reducing the rate the Fed pays on the reserves held at the Fed from the current 25 basis points as a way to encourage banks to put that money to work, although where exactly they put it to work is not part of the concern. Just do something with it. That is a development we will need to watch.

The Unintended Consequences of ZIRP

Off the top of my head I can come up with four ways that the proposed extension of ZIRP can have consequences other than those outlined in the papers. We will look briefly at each of them, although they each deserve their own letter.

To continue reading this article from Thoughts from the Frontline – a free weekly publication by John Mauldin, renowned financial expert, best-selling author, and Chairman of Mauldin Economics – Please Click Here.


Here's our up coming FREE trading webinar schedule....don't miss out!


Monday, November 18, 2013

Option Probabilities Spell Possible Trouble for Treasury’s

Our trading partner J.W. Jones is coming at us today with a great post on where he sees the Treasury ETF TLT headed. Great guidance for where the market at large just might be headed.....

The incredible rally in equities in 2013 has begun to stir concern among many that the stock market is now in a bubble. We have entered the euphoric stage of this bull market and equity prices cannot and will not go lower according to some talking heads in the financial punditry.

While chatter is starting to heat up that equities are in a bubble, the real bubble seems to be ignored for the most part. The larger, more concerning bubble is in the Treasury marketplace where the Federal Reserve continues to print money to purchase treasury bonds to help keep interest rates artificially low.

Instead of debating the bubbles in Treasury’s versus equities, or trying to predict when the bubble in either asset class may pop, I want to focus on the near term for price action expectations in longer dated Treasury bonds.

Here is a weekly chart of the Treasury ETF TLT which is supposed to reflect the price action and yield generation of a portfolio of 20+ year duration Treasury bonds issued by the U.S. federal government.....Read "Option Probabilities Spell Possible Trouble for Treasury’s" 


"Wall Streets Best Kept Secret....Now you are in the loop"


Monday, July 30, 2012

The Federal Reserve, Gold, Crude Oil and the Dollar’s Demise

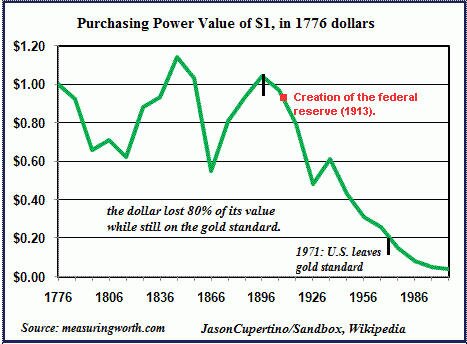
The Federal Reserve through its various monetary mechanisms has a major impact on the value of the U.S. Dollar and over time has destroyed the purchasing power of the fiat base currency used in the United States.
Interestingly enough, the following quote comes directly from the Federal Reserve’s website regarding one of its primary mandates, “In setting monetary policy, the Committee seeks to mitigate deviations of inflation from its longer-run goal and deviations of employment from the Committee’s assessment of its maximum level.”
The chart below illustrates the horrific job the Federal Reserve has done of protecting the purchasing power of the U.S. Dollar since its creation.
Dollar Creation By The Federal Reserve
In light of the longer-term malaise seen above, the Dollar Index futures have recently rallied sharply higher as Europe continues to flail in a slow and agonizing decline which will ultimately lead to a complete fiscal disaster.
Sovereign debt concerns continue to mount regardless of what the European technocrats spew publicly and the U.S. Dollar has been the primary beneficiary of these seemingly growing concerns.
This brings me to the purpose of this article. Most of the articles I write are focused on option based trades, but I decided it was time to put forth a more comprehensive scenario that could unfold over the next few years as a result of excessive monetary stimulus through various quantitative easing mechanisms developed by the Federal Reserve Bank.  “A mild change” to say the least . . .
As discussed above, the U.S. Dollar Index futures have moved higher throughout most of 2012. Any significant increase in the U.S. Dollar is a growing concern among central bankers as it correlates toward deflation. Deflation is the Fed’s biggest enemy, besides themselves of course.
Next week the Federal Reserve will release statements relating to the economic condition of the United States. Furthermore, the Fed also will discuss if it will initiate another dose of monetary crack for a capital market place that is addicted to cheap money and zero interest rates. At this point, the so-called marketplace is the antithesis of free by all standard measures.
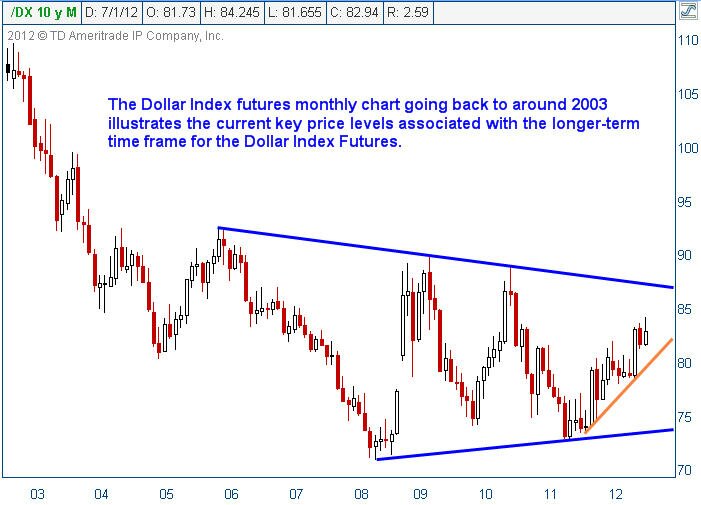
Consider the long-term monthly chart of the U.S. Dollar Index futures illustrated below:
Dollar Index Value Chart
The U.S. Dollar Index futures are in an uptrend that dates back to mid 2011. The orange line illustrates the uptrend and represents a key price level for the U.S. Dollar Index. For those unfamiliar with basic technical analysis, the rising orange trendline will act as buying support until the Dollar eventually breaks down through it signaling the bullish move higher has ended.
This brings us to a rather interesting potential observation. Today Mario Draghi, Chairman of the European Central Bank (ECB), made public comments regarding the readiness of the ECB to act if need be to safeguard the European Union. The Dollar Index Futures plummeted on the statement and remained under selling pressure most of the trading session on Thursday.
If a mere comment from the ECB can have such a damaging impact on the valuation of the Dollar, what would happen to the Dollar if the Fed initiated a new easing mechanism?
The answer is simple, the U.S. Dollar would immediately be under selling pressure. Selling pressure in the U.S. Dollar Index generally leads to a rally in risk assets such as equities and oil futures. Over the longer-term, a weak Dollar is also positive for precious metals and other hard assets.
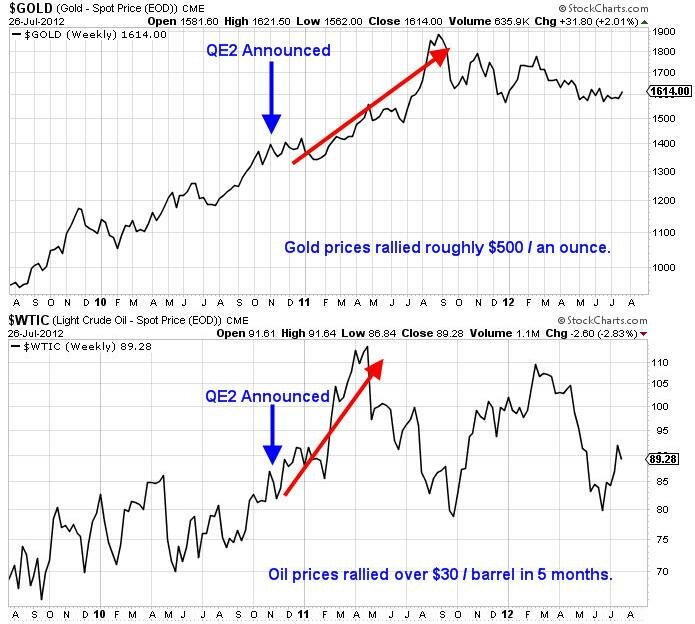
As an example to illustrate the power of Quantitative Easing as it relates to the price of both gold and oil, consider the following chart:
Spot Gold Price Chart
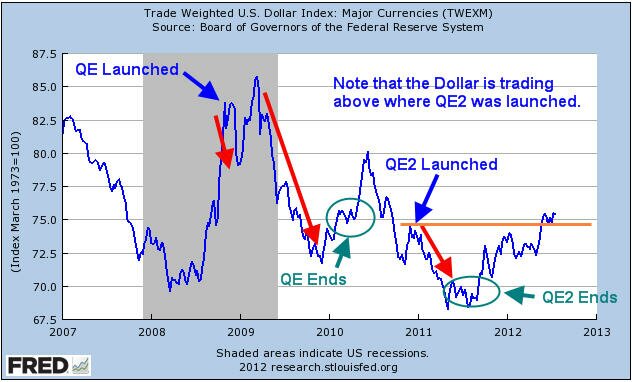
Obviously the price action is pretty clear that Quantitative Easing has a positively correlated impact on the price performance of hard assets, specifically gold and oil. Now consider a price chart of the Dollar Index shown below courtesy of the Federal Reserve Bank, the annotations are mine.
Quantitative Easing Effects
The chart above tells an interesting story about the impact that Quantitative Easing has on the Dollar. How can the Federal Reserve claim to be protecting the purchasing power of the U.S. Dollar when its actions have a direct negative correlation to the greenback’s price?
Furthermore, based on the chart above I am of the opinion that Quantitative Easing III is a foregone conclusion. The current price of the Dollar Index is clearly above the previous high where QE2 was launched. So far, the rally in the Dollar Index has not pushed equity prices considerably lower. However, should the Federal Reserve refrain from initiating additional easing measures it is likely based on the chart above that the U.S. Dollar Index will rally.
Upon the conclusion of both QE and QE2, the Dollar Index rallied sharply higher. With the Fed announcement coming closer by the hour, financial pundits will attempt to predict the future action of the Fed.
I have no interest in making predictions about what the Fed will do. It is a certainty that QE3 will take place at some point in the future whether it be sooner or later. The Federal Reserve simply has no choice, otherwise the Dollar would continue to rally and we would begin to go through a deflationary period which the Federal Reserve simply cannot tolerate.
The scenario that I would urge inquiring minds to consider would be as follows. If the Fed does nothing we can likely assume that the U.S. Dollar Index will continue to rally to the upside. Based on the price chart of the U.S. Dollar Index shown above, we can expect that sellers would certainly step in around the 86 – 88 price range based on previous resistance.
If the U.S. Dollar makes it anywhere near the 86 – 88 price range without the Federal Reserve initiating QE3 it would be expected that risk assets would be under considerable selling pressure somewhere along the way. Should the Fed act to break the Dollar’s rally either through more easing or “other” mechanisms, the result would be a potentially monster rally for risk assets, at least initially.
Equities, oil, and precious metals would rally on a falling Dollar as shown above. The question then becomes what if this is the last gasp rally before a monster selloff ensues in the Dollar Index?
If the Fed breaks the rally early or initiates a monster-sized easing program, the initial reaction will be quite positive, especially for equities. As the selloff in the Dollar Index worsens, equities would eventually begin to underperform as oil prices would surge putting pressure on the economy.
In addition to oil rallying on the weaker Dollar, we could also see sellers start to show up in droves dumping U.S. Treasury’s to any buyer left standing. International debt holders would especially have incentive to sell Treasury’s as the real purchasing power of the bonds’ interest payments would decline as the Dollar fell in value.
The way I see it, whether the Fed launches QE3 now or later, the outcome will not change. An extremely weak Dollar could wreak havoc across a variety of assets and the broader economy. Imagine where gasoline prices would be if oil prices hit $125 / barrel. The average price in the U.S. would be well above $5 / gallon based on current prices and possibly higher.
What happens to the economy if interest rates start to react violently to the price action in the Dollar? What if Treasury’s start to sell off viciously and interest rates start to rise wildly and volatility among bond holdings runs rampant? Are we to believe that the very entity that has created boom and bust cycles through easy monetary policies and has been oblivious to the bubbles that it has created is capable of solving the issues that would potentially arise from a currency crash in the U.S. Dollar?
The track record of the Federal Reserve is quite clear. They are generally late to the party and rarely are able to forecast events in the future with any clarity. Do you really think they will know what to do? The free market wants to destroy debt through deflationary pressure and price discovery and the Federal Reserve continues to get in the way.
The free market will win as it always does, but the American people will lose. This process may take months, years, or even decades to play out. Eventually the game will end. There is only one certainty should any portion of the scenario discussed above come to fruition, when the Dollar is inevitably broken the only safe place to hide during the potential currency crash will be in physical gold and silver. Paper money and paper assets will come under extreme selling pressure and in some cases will simply........disappear.
Here’s to hoping I am totally wrong!
Test drive our video analysis and trade idea service for only $1 at www.Trader Video Playbook.com


Get our Free Trading Videos, Lessons and eBook today!

Sunday, June 12, 2011

What the U.S. Dollar and the Euro Mean to the S&P 500

The buzz around the blogosphere and in the media is that Quantitative Easing II is scheduled to end in around 3 weeks. Already pundits are asking about Quantitative Easing III as a matter of when, not if. In reality a QE III Lite version is already in the cards as the Federal Reserve has stated they will be buying Treasuries and Mortgage Backed Securities (MBS) with maturing issues. The Fed also plans on reinvesting the interest earned from the existing portfolio (Roughly $15 billion/monthly).

When it comes to the application of financial principles, doing the opposite of what everyone else does generally leads to an extreme variation in the overall results. While the results are not always better, they are at the very least significantly different from what most lemmings within the group experience. In every aspect of my financial life I try to do the opposite of what the herd is doing. It takes experience and a significant level of discipline, but buying from the herd when they are selling and being willing to sell into a crowd when they are buying is a great way to trade. It sounds easy, but for most people it is not, myself included.

Right now financial markets are uncertain. I would be remiss if I did not point out the recent strength in the U.S. Dollar Index and the potential higher low that it has carved out on the daily and weekly charts. The weekly chart of the U.S. Dollar Index is shown below:


The current pattern on the U.S. Dollar Weekly chart is bullish. We could see the U.S. Dollar Index trade significantly higher from here as it has been under severe selling pressure for an extended period of time. While I believe technical analysis is just one context through which to view financial markets, it is uncanny how often market cycles and headline events line up. Is it merely a coincidence that the U.S. Dollar is potentially bottoming around the same time the Federal Reserve is ending the QE II asset purchase program?

Regardless of what camp economists are in, we presently live in a strange time for financial markets and capitalism in general. One of the more interesting charts to study is the Euro currency, which in contrast to the U.S. Dollar Index appears to have a more bearish pattern. Could it be that the U.S. Dollar is setting up to rally because of the perceived weakness of the Eurozone? The daily chart of the Euro ETF is shown below:


The Dollar may be firming up here based on the Euro’s weakness and it may have absolutely nothing to do with QE II ending. I always refer to price action and never question Mr. Market’s directional bias. If the U.S. Dollar begins to work higher what impact will it have on equities?

A stronger U.S. Dollar would certainly put pressure on risk assets, specifically equity and commodity prices. As it turns out, we are at an interesting juncture in financial markets at this point in time.
The 4 year stock market cycle is nearing an end, a presidential election will take place in less than 18 months, the U.S. government has a massive debt crisis developing, and the European debt crisis continues to mature in what will likely be a microcosm of what we will face here in the United States. The Middle East remains tense at the very least and the recent OPEC announcement to maintain supply levels has helped support oil prices.

Higher oil prices have obviously slowed down the U.S. economy as the consumer is strapped with higher costs on nearly everything, specifically food and energy. In addition, the unemployment numbers are seemingly not improving and housing appears to be rolling over . . . again.

Almost everywhere we look the news is bleak. Mr. Market has shrugged off bad news time and time again since the March 2009 lows. The long term shorts remain frustrated to say the least and those who were actively shorting along the way have likely been stopped out multiple times. Everywhere I look market commentary is bearish and pundits are talking about additional weakness as they point to a rallying Dollar and multiple economic headwinds facing domestic markets.

Traders and investors should be focused on a few specific price levels on the S&P 500. With the Dollar rallying, the S&P 500 index has remained under extreme selling pressure for multiple weeks. The S&P 500 (SPX) is likely going to test its 200 period moving average. From there I am expecting a bounce higher, although the bounce may be nothing more than a Dead Cat Bounce.

As always, time and price will be the final arbiter but if the Dollar continues to trade higher we could see the S&P 500 lose its 200 period moving average and eventually test a major support level which needs to hold up for the bulls. If the March 16, 2011 pivot lows are taken out to the downside, the next leg of the secular bear market may be under way. The daily chart of the SPX illustrated below shows the key price levels and the potential price action that may lead up to a key test of the March 2011 pivot lows:


Very rarely does the first mouse get the cheese, so I would anticipate a bounce off of the 200 period moving average which currently coincides with the March pivot lows. With not only the pivot lows but the 200 period moving average offering support a breakdown lower will be a large tell about the health and future price action of the S&P 500.

Right now I am just going to focus on how the S&P 500 handles the key support zone illustrated above. The forthcoming price action will tell traders everything we need to know about the health of financial markets. I have no idea if we are about to enter a double dip recession nor do I know whether price action will even test the March pivot lows.

What I do know is that price action in coming days around key support areas is going to be critical. I am convinced that Mr. Market will tell us whether the bullish party will continue or come to an end in the next few weeks/months. A breakdown of the March pivot lows in the future will likely initiate the launch sequence for the next secular bear market. I would keep the S&P 500 1,250 price level on the radar going forward. Risk remains high.

If you would like to receive J.W. Jones emails several times per week on SP 500, Volatility Index, Gold, and Silver intermediate direction and option trade alerts… take a look at Options Trading Signals.com today for a 24 hour 66% off coupon, and/or sign up for his occasional free updates.